Nesta página: [ocultar]
O servidor em nuvem CPX52 da Hetzner custa EUR 36.49 um mês depois 14 Junho 2026. Na manhã seguinte custou EUR 100.49. Os preços de lista da nuvem passaram duas décadas indo em uma direção, baixa. Este ano eles viraram. Below are the cloud hosting numbers we could trace to whoever published them. Market size, who actually hosts the web, what a server costs today. One popular figure turned out to be a five-year-old forecast.
Resposta rápida: Cloud spending is growing faster than at any point in eight years, but the money and the websites are moving to different places. These are the figures that hold up:
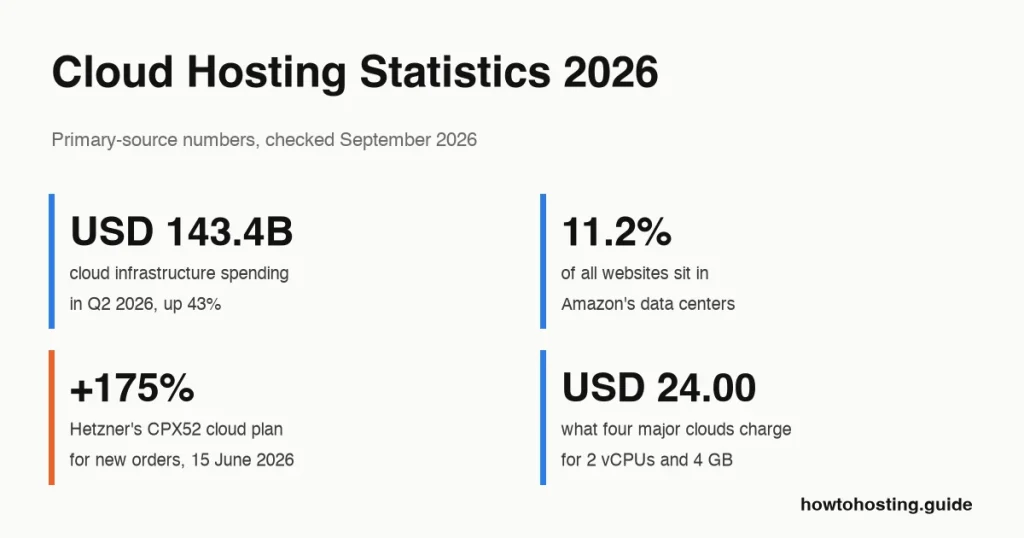
- Enterprises spent USD 143.4 billion on cloud infrastructure services in Q2 2026, acima 43% on a year earlier, according to Synergy Research Group.
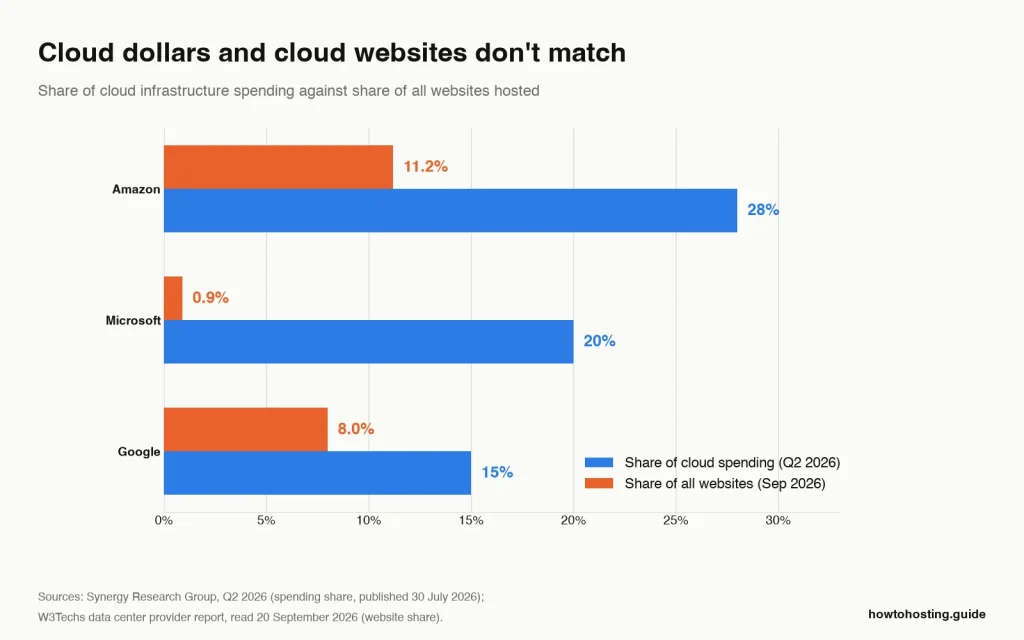
- Amazon takes 28% of that spending, Microsoft 20% e o Google 15%.
- Amazon is the data center provider for 11.2% de todos os sites, Google for 8.0% and Microsoft for 0.9%, per W3Techs on 20 setembro 2026.
- Hetzner raised prices on every cloud plan for new orders on 15 Junho 2026. Its CPX52 went up 175% in euros.
- De 1 Outubro 2026, OVHcloud bills local storage and public IPv4 as separate lines on its Generation 3 instâncias.
- Four large clouds charge exactly USD 24.00 um mês para 2 vCPU, 4 Servidor GB: DigitalOcean, Vultr, Akamai Cloud and AWS Lightsail.
- Flexera’s March 2026 survey of more than 750 cloud decision-makers put wasted cloud spend at 29%, the first rise in five years.
Última revisão: setembro 2026. Preços e recursos verificados.
Where the Numbers Come From
One rule decided what made this page: we had to reach the organization that produced the figure, not a blog quoting it. Market data comes from Synergy Research Group’s own quarterly releases and from Gartner’s press releases, each with its publication date shown. Anything we could only find on statistics round-ups got cut, including one figure our previous version of this page used.
Website-level counts come from W3Techs, which surveys more than 20 million sites drawn from the Chrome User Experience Report and a customized Tranco list. Its reports refresh daily, so every W3Techs figure here carries the date we read it: 20 setembro 2026.
Prices were read the same day from provider pricing pages, price-change notices and one vendor pricing API. Where a provider publishes euros only, we give the euro figure rather than converting. A conversion date goes stale faster than the price does.
Now the limits. We didn’t buy any paid market report, so segment splits behind paywalls aren’t here. We ran no benchmarks and no uptime monitoring. W3Techs counts the network a site resolves to. Buy from a reseller that runs on Amazon, and your site counts as Amazon in one table. No outro, it counts as the reseller. That quirk turns out to be useful, and there’s a whole section on it below.
How Big Is the Cloud Market in 2026?
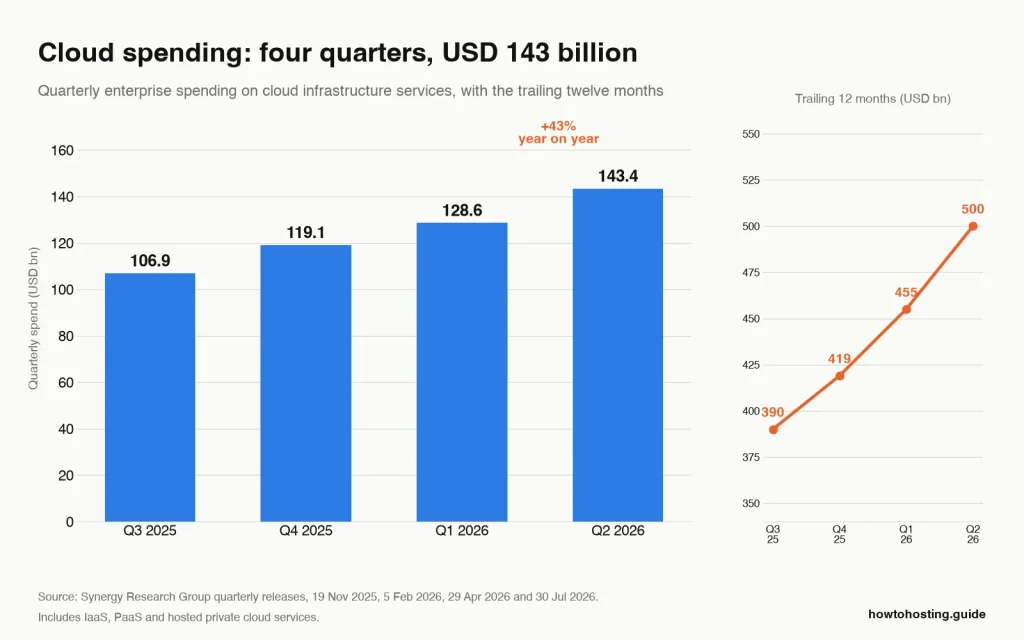
Synergy Research Group, now part of TechInsights, put Q2 2026 enterprise spending on cloud infrastructure services at USD 143.4 bilhão. That’s a jump of more than USD 43 billion from Q2 2025, and a year-on-year growth rate of 43%. It was the eleventh consecutive quarter in which the growth rate rose. Over those eleven quarters the market doubled.
Here’s the quarterly run, all from Synergy’s own releases:
- 3º trimestre 2025: USD 106.9 bilhão, trailing twelve months USD 390 bilhão
- 4º trimestre 2025: USD 119.1 bilhão, acima 30%, closing 2025 em dólares americanos 419 bilhão
- 1º trimestre 2026: USD 128.6 bilhão, acima 35%, trailing twelve months USD 455 bilhão
- 2º trimestre 2026: USD 143.4 bilhão, acima 43%, trailing twelve months USD 500 bilhão
Gartner counts a narrower slice and gets a smaller answer. Está 27 Julho 2026 previsão puts worldwide infrastructure as a service spending at USD 287 bilhões em 2026. That’s up 29.3% de USD 222 bilhões em 2025. Synergy’s USD 500 billion also includes platform services and hosted private cloud, which Gartner files elsewhere. Both are right. They’re measuring different things, so name the firm whenever you quote either one.
Something in that Gartner release is easy to miss. In the April 2026 previsão, IaaS was still folded into a single IT services line worth USD 1.87 trilhão. By July it had its own row. So if you’re holding a 2026 cloud forecast next to an older one, check where IaaS was sitting in each.
Hardware, not cloud services, is Gartner’s fastest-growing line. Data center systems spending is forecast at USD 822 bilhões em 2026, acima 62.5%. That’s more than twice the growth rate of the cloud services sold on top of it. In this data, that’s the clearest signal that the 2026 cost problem starts in the supply chain.
O dólar 947.3 Billion Figure Is a 2021 Forecast
Cloud statistics pages love one number: USD 947.3 bilhões por 2026, growing 16.3% um ano. Our own previous version of this page carried it, with no date attached.
It traces to a MarketsandMarkets press release published on 28 Outubro 2021, forecasting the 2021-2026 window from a base of USD 445.3 bilhão. The arithmetic is fine. The problem is the vintage. It was written before generative AI reshaped cloud demand. o 16.3% growth it assumed is less than half the 43% Synergy measured in Q2 2026. If you see USD 947.3 billion quoted for 2026, check whether the page tells you it’s a 2021 previsão. Most don’t.
Quota de mercado: Amazonas 28%, Microsoft 20%, Google 15%
Synergy’s 30 Julho 2026 liberação gives worldwide Q2 2026 shares of 28% for Amazon, 20% for Microsoft and 15% for Google. Juntos isso é 63% of all cloud infrastructure services. Narrow the definition to public IaaS and PaaS and the same three take 67%. PaaS is platform as a service: the managed databases and app runtimes sold on top of raw servers.
Track the trend and Google is the one moving. Across four Synergy quarters its share went 13%, 14%, 14%, 15%. Amazon went 29%, 28%, 28%, 28%. Microsoft sat at 20% ou 21% por todo. Amazon isn’t shrinking. It’s growing more slowly than a market expanding 43% um ano.
Below the top three, the newcomers are the story. Nine neocloud companies, the GPU-first providers built for AI training, now sit among the top 40 cloud providers by infrastructure revenue. Synergy names CoreWeave, OpenAI, Oráculo, Crusoe, Nebius, Anthropic and Nscale among the fastest growers. In Q1 2026 it put neoclouds at roughly 5% do mercado total. GenAI-specific cloud services grew 165% year on year in Q2.
Europe’s own providers hold a much smaller slice at home. Synergy’s 24 Julho 2025 analysis put European providers at about 15% of the European cloud market, para baixo de 29% no 2017. Amazonas, Microsoft and Google take 70% entre eles.
How Many Websites Run on Cloud Hosting?
Spending tells you about enterprise workloads. It says very little about websites. Para isso, W3Techs is the better measure, because it looks at where a site’s server actually sits.
Em 20 setembro 2026, its data center provider table read like this:
- Amazonas: 11.2% de todos os sites
- Google: 8.0%
- Hostinger: 5.2%
- OVH: 2.7%, Internet Unida: 2.7%, Squarespace: 2.5%
- Hetzner: 2.4%, team.blue: 2.1%, GoDaddy Group: 1.9%
- DigitalOcean: 1.5%, Oráculo: 1.4%, Microsoft: 0.9%
Add the four hyperscalers together, Amazonas, Google, Oracle and Microsoft, e você recebe 21.5% de sites. That’s roughly one site in five on infrastructure owned by a company that also sells AI compute. The other four in five sit with hosting companies, site builders and regional providers.
Microsoft is the outlier worth staring at. Azure earns one cloud dollar in five and appears under 1% de sites. It’s an enterprise workload platform, not a website platform. For anyone shopping for hosting, its market share is the wrong number to care about.
Cloud Dollars and Cloud Websites Are Two Different Markets
Put the two tables side by side and the gap is hard to unsee. W3Techs publishes two of them. One records whose facility the server sits in. The other records who sold the hosting. Same day, same sample.
- Amazonas: 11.2% as data center provider, 4.5% as hosting provider
- Google: 8.0% as data center provider, 1.7% as hosting provider
- Hetzner: 2.4% e 2.1%, almost identical
- Hostinger: 5.2% e 5.2%, identical
Do the division and 60% of Amazon-hosted sites bought their hosting from somebody else. For Google it’s 79%. Hetzner and Hostinger own their racks and sell direct, so their two numbers match.
Resellers show up on the other side of the ledger. Shopify is the largest single web hosting provider at 5.4% of websites and appears nowhere in the data center table. Vercel holds 2.1% as a hosting provider and also has no data center entry. Both run on other people’s infrastructure. A managed platform such as Cloudways does the same thing openly. It resells DigitalOcean, Vultr, Akamai, AWS and Google Cloud capacity with a control panel on top. Nosso comparação de alojamento cloud gerido covers that layer in detail.
So what? Two practical things. Primeiro, “runs on AWS” is a marketing line, not a differentiator, because more than one site in ten already does. Segundo, buying from a reseller means you inherit two companies’ outage histories and two companies’ price decisions. Only one of them sends you an invoice.
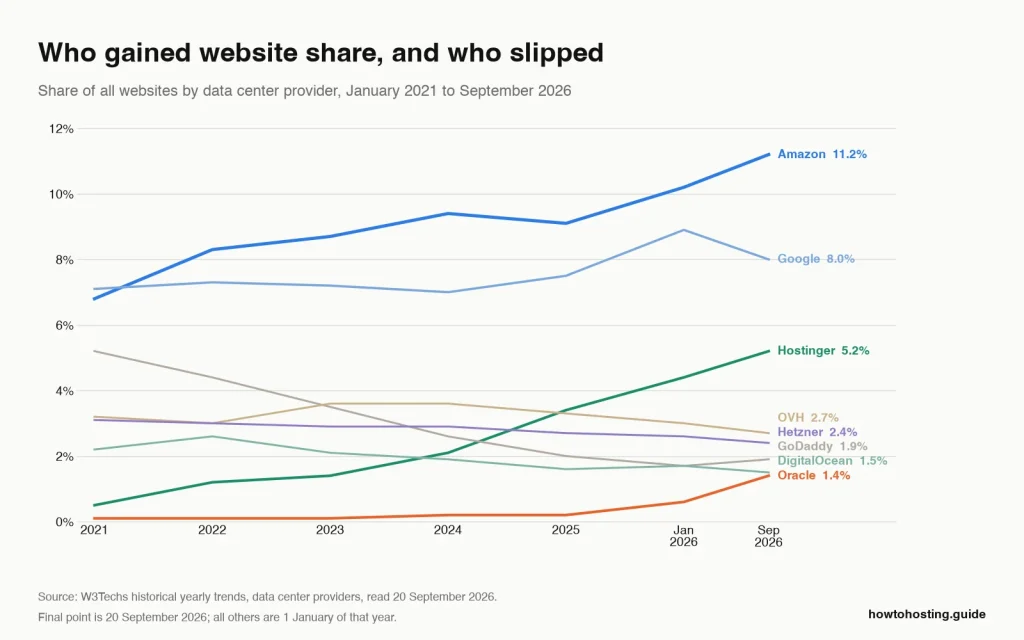
Five Years of Website Share: Who Gained and Who Slipped
W3Techs keeps a yearly history back to January 2021, which turns a snapshot into a direction. Data center provider share, janeiro 2021 contra 20 setembro 2026:
- Amazonas: 6.8% para 11.2%
- Google: 7.1% para 8.0%
- Hostinger: 0.5% para 5.2%
- Oráculo: 0.1% para 1.4%
- Hetzner: 3.1% para 2.4%
- OVH: 3.2% para 2.7%
- DigitalOcean: 2.2% para 1.5%
- GoDaddy Group: 5.2% para 1.9%
Oracle is the sharpest move on the board. It sat at 0.1% for three straight Januaries, alcançado 0.2% em janeiro 2025, then hit 1.4% by September 2026. That’s seven times bigger in twenty months. Oracle’s free tier and its AI hosting deals both land in that window, and W3Techs data alone can’t separate them (we tried).
Meanwhile the three names a developer would call “Armazenamento em nuvem” all went backwards. Hetzner, OVH and DigitalOcean each lost website share while the cloud market doubled in dollars. Their revenue may well be up. Their slice of the web is not.
Cloud Hosting by Country: Where the Servers Sit
W3Techs also records server location for the sites where it can determine one. Em 20 setembro 2026 the United States held 33.0%, with Germany second on 15.4%.
- Estados Unidos: 33.0%
- Alemanha: 15.4%
- Japão: 6.0%
- França: 5.2%
- Países Baixos: 3.7%
- Rússia: 3.5%, Reino Unido: 2.7%, Brasil: 2.6%, Itália: 2.2%, Índia: 2.0%
Germany’s 15.4% is the number worth pausing on. It’s nearly three times the French figure and more than five times the British one. For a country with a smaller economy than either the US or Japan, that’s a lot of servers. Hetzner, IONOS and a dense field of regional hosts all run German capacity. German data protection rules give local buyers a reason to stay put. The same logic drives demand in Austria, Switzerland and the wider Central European market. Lá, an EU data center is often the first filter a buyer applies.
Sovereign Cloud: Europe’s Spending Triples by 2027
Gartner gave that instinct a price tag. Está 9 fevereiro 2026 previsão puts worldwide sovereign cloud IaaS spending at USD 80.4 bilhões em 2026. That’s up 35.6% de USD 59.3 bilhões em 2025, and it reaches USD 110.6 bilhões em 2027.
Europe is the fastest-moving large region. Gartner’s table takes European sovereign cloud IaaS spending from USD 6.87 bilhões em 2025 para USD 12.59 bilhões em 2026. No 2027 it reaches USD 23.12 bilhão. Isso é 3.4 times in two years, and it puts Europe ahead of North America in 2027, forecast at USD 21.13 bilhão. China leads throughout, em dólares americanos 47.4 bilhões em 2026.
There’s a second finding in the same release. Gartner estimates that sovereign cloud demand will shift 20% of current workloads from global to local cloud providers, a move it calls geopatriation. For a regional host, that’s the most encouraging number on this page. For a buyer, it means the local provider you dismissed as small is about to have more customers, and possibly a waiting list.

Sovereign cloud IaaS spending by region. Europe passes North America in 2027. Fonte: Gartner, fevereiro 2026.
What Cloud Hosting Costs in September 2026
Start with the number people actually come for. The honest answer starts around USD 3 a month and has no ceiling. One bit of jargon first, since it’s in every line below. A vCPU is a virtual processor core, shared with other customers unless the plan says so. Here are entry prices we read on 20 setembro 2026, cheapest first:
- Vultr Regular Performance, Somente IPv6: USD 2.50 um mês para 1 vCPU, 0.5 GB e 10 GB de armazenamento. With an IPv4 address it’s USD 3.50.
- DigitalOcean Basic: USD 4.00 um mês para 1 vCPU, 512 MiB and 10 GiB.
- AWS Lightsail: USD 5 um mês para 2 vCPUs, 0.5 GB, 20 GB e 1 TB de transferência.
- Akamai Cloud Nanode 1 GB: USD 5.00 um mês para 1 vCPU, 1 GB e 25 GB.
- Hetzner CAX11: EUR 5.99 um mês, acima de EUR 4.49 antes 15 Junho 2026. Hetzner’s own table puts that at USD 6.99, and its cloud servers ship without a public IPv4, which adds EUR 0.50 (USD 0.60).
- Contabo Cloud VPS 4: EUR 6.55 a month excluding VAT on a 24-month term, para 4 Núcleos de vCPU, 8 GB e 100 GB. The page shows EUR 9.41 atingido.
- Cloudways Flexible Micro: USD 14 um mês para 1 vCPU, 1 GB e 25 GB de NVMe, com gestão incluída.
Two things hide in that list. The first is the IPv4 address, which several providers now price separately, so a headline figure excluding it isn’t the bill. The second is management. Cloudways charges USD 14 para 1 Servidor GB. DigitalOcean sells the same thing direct for USD 6, so the managed layer costs 2.3 vezes o servidor bruto.
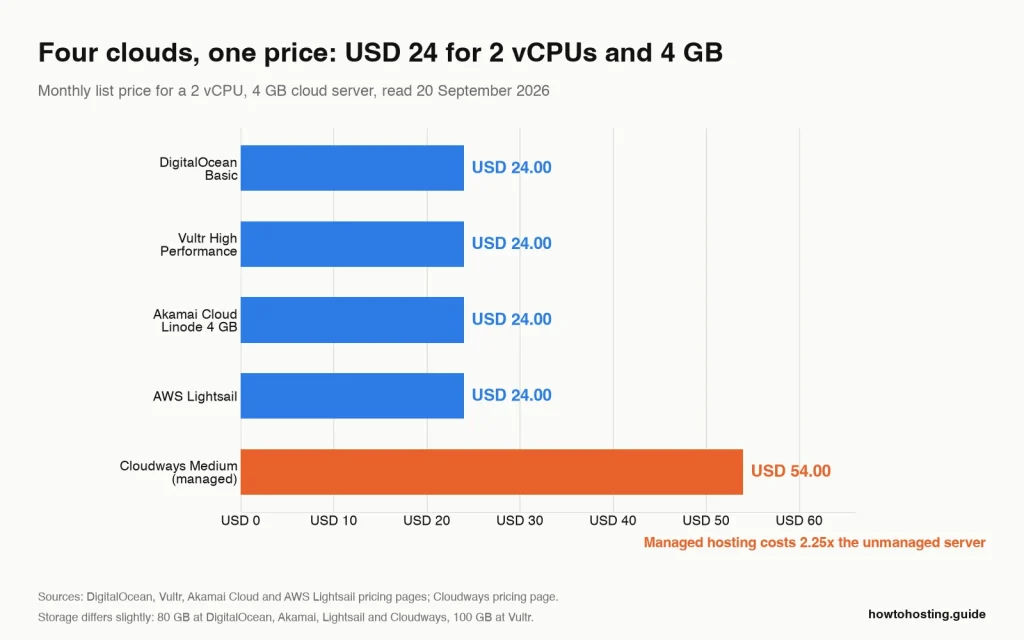
Now compare like with like. Ask four large clouds for 2 vCPUs e 4 GB of RAM and they quote the same number:
- DigitalOcean Basic, 4 GiB, 80 SSD de GiB: USD 24.00
- Vultr High Performance, 4 GB, 100 GB NVMe: USD 24.00
- Akamai Cloud Linode 4 GB, 80 GB: USD 24.00
- AWS Lightsail 4 GB, 80 GB SSD: USD 24
- Cloudways Medium, 4 GB, 80 GB NVMe, gerenciou: USD 54.00
Four unmanaged clouds, um preço, para o centavo. The managed version of the identical specification costs 2.25 times as much. That’s the cleanest number we have on what server management is worth in 2026.
That European discount at this size has narrowed too. Hetzner’s CPX22, a two-core shared plan, custo em USD 9.49 a month before 15 Junho 2026 and costs USD 22.99 agora. A plan that sat far below the USD 24 cluster now sits just under it. For the sub-USD-10 end of the market, nosso comparação de hospedagem na nuvem barata maps it out.
o 2026 Price Rises, Com datas
Cloud servers bill you for all of their memory, and memory got expensive fast. OVHcloud designs and assembles its own machines, so it sees that bill first. In August it put the problem plainly: “Buying memory costs us six times more today than it did a year ago.” Three providers moved, each in its own way.
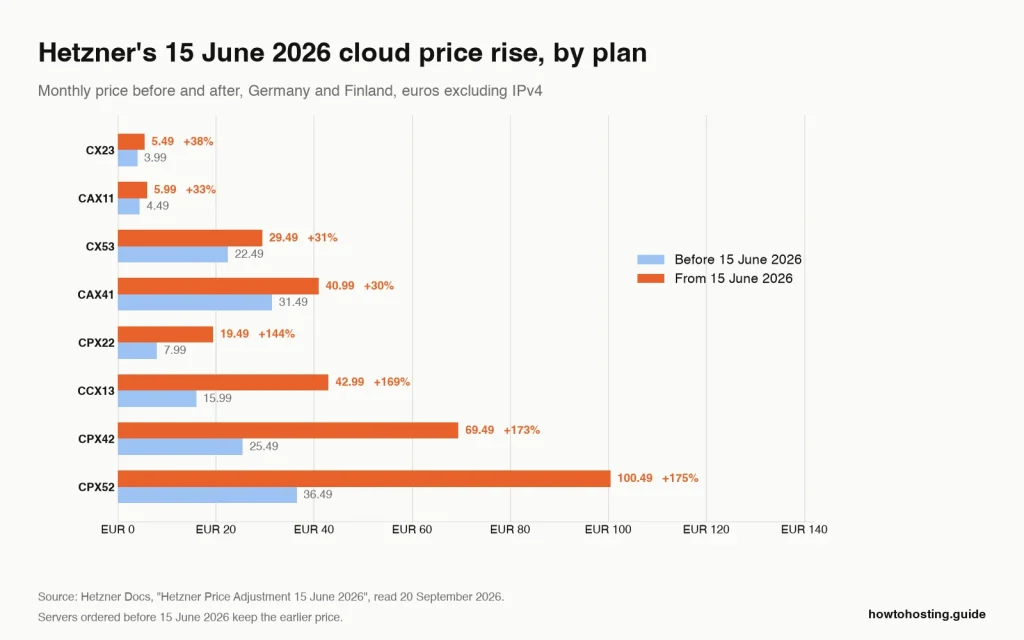
Hetzner, 15 Junho 2026. Every cloud plan and dedicated server was repriced for new orders at 8 AM CEST. The rise split by plan family, not by plan size, and the spread is enormous. In Hetzner’s own euro table for Germany and Finland, the entry CX line rose 31% para 38%. The cost-optimized CAX line rose 30% para 33%. The shared-vCPU CPX line rose 144% para 175%, and the dedicated-vCPU CCX line 113% para 173%. Orders placed before that morning keep the old rate, though rescaling an existing server can move it onto the new one.
Some individual moves are brutal. CPX22 went from EUR 7.99 é EUR 19.49 um mês, and CCX13 from EUR 15.99 é EUR 42.99. Hetzner’s CPX52 went from EUR 36.49 é EUR 100.49 um mês depois 15 Junho 2026, a rise of 175%. Hetzner blamed “the massive increase in procurement costs” and cut most dedicated server setup fees at the same time.
OVHcloud, April and October 2026. Founder Octave Klaba wrote on 5 marcha 2026 that RAM prices could rise 250% para 300% no final de 2026, against September 2025. He added that providers must now order memory up to twelve months ahead, without knowing the final price. OVHcloud capped its own April increase on Public Cloud, Private Cloud and Bare Metal at 9% para 11% na média. Older deployments rose 2% para 6%.
A bigger change lands on 1 Outubro 2026. Local storage and public IPv4 stop being included on Generation 3 instâncias, the B3, C3 and R3 families. Local storage becomes a billable class at EUR 0.0001458 per GB per hour, sobre euros 0.11 por GB por mês, ou euros 109 per TB. A public IPv4 address costs EUR 0.0027 uma hora, sobre euros 1.97 um mês, billed even while unattached. So an address you forgot about still costs you. The hourly compute price doesn’t change. OVHcloud puts the resulting bill increase at 1.4% para 21.9%, and the smaller your instance, the harder it lands.
Savings Plans change on the same date. o 1, 6 and 24-month terms disappear, saindo 12 meses em 15% desligado e 36 meses em 30% desligado, both lower discounts than before. Those discounts apply to compute only, so the new storage and IP lines are charged at full rate even inside a running commitment. B2, C2, R2 and earlier instances keep their included storage.
AWS, em andamento. Amazon’s EC2 Capacity Blocks pricing page now states that “reservation prices are updated regularly based on trends in supply and demand.” It adds that “the current prices are scheduled to be updated next in October, 2026.” A p5e.48xlarge reservation listed at USD 47.76 an hour on 20 setembro 2026. Publishing a scheduled repricing date, rather than a price cut, is a change of posture. This is the company that trained the industry to expect the opposite.
Taken together, that’s the 2026 pattern, and it isn’t the obvious one. The increases didn’t track plan size, and they didn’t track memory either. Hetzner’s rises sorted by processor family. OVHcloud’s land hardest on the smallest instances. What all three share is a direction: the all-inclusive price is coming apart.
One forward look, and this one’s opinion rather than measurement. Expect more of your bill to arrive as separate components you can switch off, and expect like-for-like comparison to get harder as it does. That’s our read of the changes above, not a figure anyone published.
What Buyers Do With the Money: 29% of It Is Wasted
Flexera’s 2026 State of the Cloud Report surveyed more than 750 cloud decision-makers. publicado em 18 marcha 2026, it put estimated wasted cloud spend at 29%. That’s the first increase in five years, and Flexera attributes it to AI workloads and the cost complexity that comes with them.
Dig into the rest of that survey and the picture fills in. Managing cloud spend is the top challenge for 85% dos entrevistados. Among large enterprises, 76% spend more than USD 5 million a month on cloud. Generative AI use reached 81%, a partir de 72% um ano antes, e 45% now run AI extensively in production. Enquanto isso 63% have a FinOps team and 73% run hybrid setups, keeping some workloads on hardware they control.
Read those together and a pattern appears. Organizations got better at cost discipline and still lost ground, because the thing they were disciplining changed shape underneath them. If nearly a third of enterprise cloud spend delivers nothing, a fixed monthly server bill looks better than any vendor comparison chart.
Putting These Numbers to Work
A number that changes nothing is trivia. Here are four buying decisions these ones should move.
Orçamento abaixo de USD 10 um mês, running a WordPress site or a small app you administer yourself. Take DigitalOcean’s USD 6.00 Basic droplet at 1 GiB, or Akamai Cloud’s Nanode at USD 5.00 for the same memory and 25 GB de armazenamento. Hetzner’s CAX11 is no longer the automatic answer at this size. Em euros 5.99 mais euros 0.50 for an IPv4 address, Hetzner’s own USD figures put it near USD 7.59, above both. Check the specification before assuming it’s better value, because Hetzner’s page wasn’t showing plan specs when we looked. Pule Cloudways aqui: USD 14 para 1 GB only pays off if nobody on your team can patch a server.
Carga de trabalho: estável 4 GB production site, and you’re comparing quotes. Stop treating the price column as the deciding one. Em 2 vCPUs e 4 GB, DigitalOcean, Vultr, Akamai Cloud and AWS Lightsail all charge USD 24.00. The choice comes down to data center location, network and support. Vultr includes 5 TB of transfer against DigitalOcean’s 4,000 GiB, which matters if you serve media. Pague em dólares americanos 54 for Cloudways only when a managed control panel saves you more than 30 dollars of work a month.
Público: 80% EU visitors, with personal data in the database. Germany hosts 15.4% of the world’s websites, second only to the United States, so local capacity is abundant rather than exotic. Gartner expects sovereign cloud IaaS spending in Europe to reach USD 12.59 bilhões em 2026 e dólares americanos 23.12 bilhões em 2027. Shortlist providers with a named EU region rather than a vague “EU-compliant” alegar, and ask where the backups live too.
Renewal due after 1 Outubro on an OVHcloud B3, C3 or R3 instance. Your compute price holds and two new lines appear. Budget about EUR 0.11 per GB a month for local storage, mais euros 1.97 for each public IPv4 address. Then release any address you aren’t using. UMA 100 GB instance with one IP picks up roughly EUR 13 um mês. On a Savings Plan, note that the discount covers compute only, so the new lines land at full price mid-commitment.
perguntas frequentes
How much does cloud hosting cost per month in 2026?
Entry cloud servers start at USD 2.50 um mês, which is Vultr’s IPv6-only plan, ou dólares americanos 4.00 for DigitalOcean’s smallest Basic droplet. A production-sized 2 vCPU, 4 GB server costs USD 24.00 at DigitalOcean, Vultr, Akamai Cloud and AWS Lightsail. Managed cloud hosting roughly doubles that: Cloudways charges USD 54 para o mesmo 4 GB.
Which cloud provider hosts the most websites?
Amazonas, por uma margem clara. W3Techs recorded Amazon as the data center provider for 11.2% of all websites on 20 setembro 2026. Google follows on 8.0% and Hostinger on 5.2%. Microsoft, despite holding 20% of cloud infrastructure spending, appears under just 0.9% de sites.
Is cloud hosting getting more expensive in 2026?
sim, and the increases are documented. Hetzner raised prices on all new cloud orders on 15 Junho 2026, with its CPX line up 144% para 175% in euros. OVHcloud raised Public Cloud prices 9% para 11% on average in April, and unbundles storage and IPv4 from 1 Outubro 2026. Both name rising memory costs as the reason.
Is Hetzner still the cheapest cloud host?
Not on sticker price, não. Hetzner’s CAX11 went from EUR 4.49 é EUR 5.99 em 15 Junho 2026. Hetzner’s own table puts the new price at USD 6.99, before the EUR 0.50 Endereço IPv4. Vultr starts at USD 2.50 and DigitalOcean at USD 4.00. Higher up the range, Hetzner’s CPX22 went from USD 9.49 para USD 22.99 the same day. That lands just under the USD 24.00 four large clouds charge for 2 vCPUs e 4 GB.
How many websites use cloud hosting?
Depends where you draw the line. Counting only the four hyperscalers, Amazonas, Google, Oracle and Microsoft account for 21.5% of all websites in W3Techs data for 20 setembro 2026. Add independent cloud providers such as OVH, Hetzner and DigitalOcean and the figure reaches 28.1%. Most of the rest sit with shared hosting companies and site builders.
Which cloud provider is growing fastest?
Among the big three, Google. Its share of cloud infrastructure spending went from 13% no terceiro trimestre 2025 para 15% no segundo trimestre 2026, while Amazon slipped from 29% para 28%. Outside the big three, the neoclouds grow faster still. Nine of them now rank in the top 40 provedores de nuvem, and GenAI-specific services grew 165% year on year in Q2 2026.
Veredicto Final
The cloud market is posting its fastest growth in eight years, and almost none of it is about hosting websites. Amazonas, Microsoft e Google pegar 63% of a market running at USD 500 billion a year. The same three sit under 21% of the world’s websites, and Microsoft under 1%. If you’re choosing where to put a site, cloud market-share headlines are the wrong instrument. Where the servers sit and what the invoice says are the right ones.
The invoice changed this year. Hetzner repriced every cloud plan on 15 Junho 2026, and its shared-vCPU line more than doubled. OVHcloud takes storage and IPv4 out of the bundle on 1 Outubro 2026. Enquanto isso DigitalOcean, Vultr, Akamai Cloud and AWS Lightsail all landed on USD 24.00 para o mesmo 2 vCPU, 4 Servidor GB. When four independent companies quote the same cent, price has stopped doing the work. Buy on region, network and support instead.
Want names rather than numbers? Nosso resumo do melhores provedores de hospedagem em nuvem applies all of this to specific plans. Readers serving EU visitors should pair this page with our guide to the best cloud hosting in Europe. Gartner expects European sovereign cloud spending to triple by 2027. And if your load runs around the clock, the same memory squeeze reshaped bare metal, which we track in our dedicated hosting statistics.